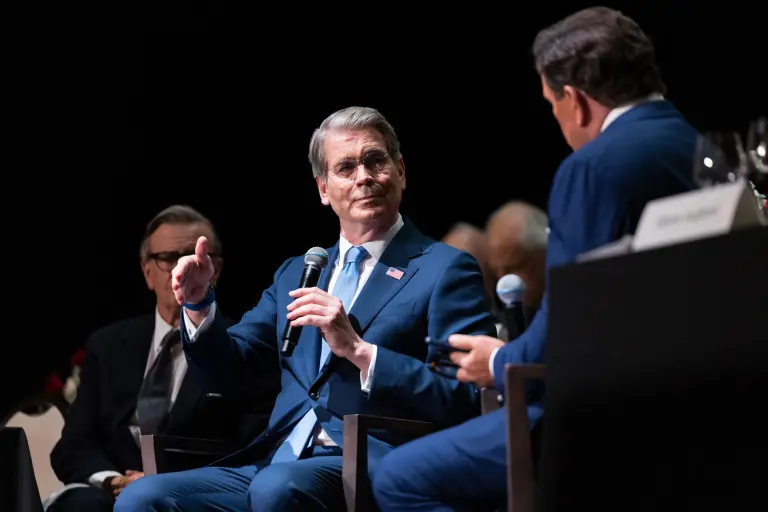
The Federal Reserve enters its September policy meeting under pressure from two very different directions, with Wall Street preparing for a possible rate increase while the White House continues to favor easier monetary policy.
For Federal Reserve chair Kevin Warsh, the Fed bond market relationship may prove particularly important. Persistent inflation and stronger-than-expected employment data have strengthened the argument for tighter policy, while rising longer-term Treasury yields could make it more difficult for the administration to push publicly for lower rates without unsettling investors.
September Meeting Puts Warsh’s Independence to an Early Test
The Federal Open Market Committee is due to conclude its September meeting on Wednesday. Investors have been preparing for the possibility that policymakers will raise the federal funds rate, a move that would run directly against President Donald Trump’s preference for lower borrowing costs.
The policy decision comes as the Fed confronts conflicting economic pressures. The latest employment report was stronger than economists had expected, while inflation remains above the central bank’s 2% objective. Higher oil prices have complicated the picture because some of the inflationary pressure reflects a supply shock rather than stronger domestic demand.
Policymakers could choose to tolerate some of that inflation rather than respond immediately. The risk is that investors interpret such restraint as a weakening commitment to price stability.
That concern has already surfaced in Treasury trading. Following the Fed’s June meeting, longer-dated government bond yields moved higher as investors absorbed hawkish signals from policymakers without a corresponding change in the policy rate.
Treasury Secretary Scott Bessent has acknowledged the political importance of that reaction. Speaking at the Economic Club of New York in June, Bessent said Trump understood the power financial markets can exert over governments.
“The bond market has taken out more governments than howitzers,” Bessent said, adding that he believed the president had confidence in Warsh to make the appropriate decision.
Rising Treasury Yields Could Limit White House Pressure
The bond market does not formally determine Federal Reserve policy, and the central bank’s mandate remains focused on maximum employment and stable prices. But Treasury yields provide policymakers with a real-time measure of how investors view inflation, fiscal conditions and the credibility of monetary policy.
If longer-term yields rise while the Fed leaves short-term rates unchanged, financing conditions can tighten regardless of what the central bank intends. Higher Treasury yields can feed into mortgage rates, corporate borrowing costs and the discount rates investors apply to financial assets.
That dynamic gives Warsh an additional layer of political protection. A rate increase can be defended primarily through inflation and employment data, while a disorderly rise in Treasury yields would demonstrate the potential cost of appearing too tolerant of inflation.
History provides a reminder of how quickly sovereign bond markets can constrain political choices. Britain’s 2022 gilt-market turmoil followed a fiscal package from then-prime minister Liz Truss’s government that triggered a sharp repricing of UK government debt. The episode forced policy reversals and contributed to intense political pressure on the government.
The US financial system is considerably larger and structurally different, but the broader lesson remains relevant. Governments can advocate lower borrowing costs, yet investors ultimately determine the yields at which sovereign debt trades.
Wall Street Warns Against a Fed Credibility Shock
Economists are therefore watching not only Wednesday’s rate decision but also the signal Warsh sends about the Fed’s willingness to act independently.
Oxford Economics chief global economist Ryan Sweet warned that bond investors could lose patience with central banks that remain inactive while inflation runs hot. If markets conclude policymakers are accepting persistently higher inflation, he argued, longer-term interest rates could rise.
UBS economist Paul Donovan has raised a related concern. A decision that significantly surprised markets could revive questions over Warsh’s independence and force investors to demand a larger risk premium on US debt. That, in turn, could increase real borrowing costs across both government and the private sector.
Bessent has also taken steps aimed at supporting Treasury-market liquidity, including a multi-billion-dollar bond buyback program that temporarily helped push yields lower.
Wednesday’s Decision Will Be About More Than One Rate Move
The immediate question is whether the FOMC raises rates. The longer-term issue is whether investors believe the Fed will continue responding to economic data when that response conflicts with the administration’s preferred policy.
Warsh is still early in his tenure, making the September meeting an important test of how markets interpret his leadership. A credible policy decision could help contain longer-term borrowing costs even if the Fed raises its benchmark rate.
The opposite outcome would be more difficult. If investors conclude political pressure is influencing monetary policy, Treasury yields could become the mechanism that tightens financial conditions instead.