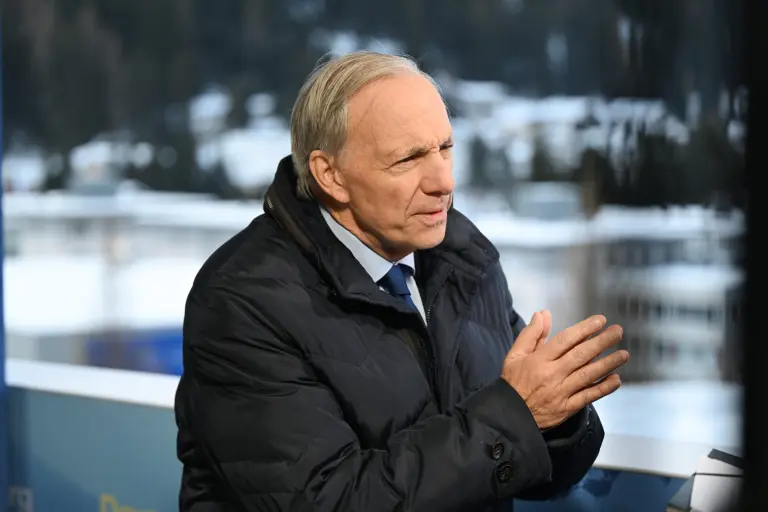
Artificial intelligence could deliver exceptional gains in economic productivity while simultaneously creating the conditions for a damaging financial correction, according to Bridgewater Associates founder Ray Dalio.
The billionaire investor argues that an AI investment bubble and genuine technological progress can exist at the same time. His warning focuses less on whether the technology ultimately succeeds and more on how capital markets behave while investors race to finance its development.
Dalio Sees a Familiar Pattern in the AI Spending Rush
Speaking in a video published by the World Economic Forum, Dalio described a recurring cycle in which important technologies attract enormous amounts of capital because investors expect them to change industries and create new sources of profit.
“There’s a process in which great new technologies are something that everybody wants to invest in because they’re going to change the world, and then they over-invest in them, and they create debt,” Dalio said.
He expects artificial intelligence to produce substantial productivity improvements. But the same enthusiasm could encourage excessive investment, rising debt and valuations that eventually become difficult to justify.
That combination, Dalio warned, could produce both significant economic gains and severe losses for investors caught on the wrong side of a market correction.
The comparison with the internet boom is difficult to ignore. The Nasdaq surged 86% during 1999 before the technology-heavy index eventually fell sharply as the dotcom bubble unwound. The collapse destroyed vast amounts of market value, even though the underlying internet technology went on to become fundamental to the global economy.
There are also reasons the current cycle may develop differently. Large companies funding today’s AI infrastructure spending include highly profitable businesses with stronger balance sheets than many speculative technology companies that attracted capital during the dotcom era.
AI Gains Could Flow Disproportionately to Asset Owners
Dalio’s second concern is distribution. The economic value created by AI may be considerable, but ownership of the companies capturing that value is concentrated among wealthier households.
“People who come up with great ideas to invent productive things receive capital that enables them to do that,” Dalio said. The process, he added, can create “very large differences in wealth.”
Federal Reserve data underline the scale of that divide. In the second quarter of 2026, the bottom 50% of US households held about $0.37 trillion in corporate equities and mutual fund shares. The top 0.1% held approximately $16.15 trillion, while households between the 90th and 99th wealth percentiles held roughly $24.01 trillion.
That matters because an AI-driven rise in corporate valuations can increase household wealth very unevenly. Workers may benefit from productivity improvements, new services or higher business output, but households with substantial equity portfolios have another channel through which they can participate directly in rising company valuations.
Dalio therefore sees the distribution of AI-generated wealth as a question extending beyond technology itself.
Productivity Optimism Is Running Alongside Investment Risk
The broader economic debate increasingly reflects the same tension.
The World Economic Forum’s September 2026 survey of chief economists found that 97% expected AI adoption to increase over the following 12 months, while 69% anticipated meaningful productivity gains. At the same time, 61% did not expect data-centre investment to account for a significant share of global job creation.
Those findings add an important dimension to Dalio’s warning. A technology can raise output without distributing the financial rewards evenly, particularly when much of the capital appreciation accrues to shareholders and founders.
There is another distinction investors will need to make. Excessive valuations in parts of the AI market would not necessarily mean the technology itself has failed. The internet survived the dotcom collapse and became essential infrastructure, even as many companies financed during the boom disappeared.
For investors, that history makes the quality of earnings, cash flow and eventual returns on enormous infrastructure investments increasingly important.
The Next Test Will Be Whether AI Spending Produces Returns
The central question is now whether the extraordinary capital flowing into AI can generate profits quickly enough to support current expectations.
Productivity gains could justify substantial investment over time. But if spending runs far ahead of commercial returns, investors may become less willing to finance projects at elevated valuations, creating pressure across technology stocks and related assets.
Dalio’s argument ultimately separates the future of AI from the future price of AI investments. The technology can succeed while individual companies, shareholders and lenders still suffer significant losses.
For markets, that distinction may become increasingly important as the AI build-out moves from expectations of future growth toward evidence of actual financial returns.